How to Document an Auto Insurance Claim After a Crash
The first minutes after a collision are about safety, followed by a factual record that can be evaluated later. It is worth considering the full decision rather than just the most visible expense or the most convenient initial fix. The right scope depends on facts that can be checked and discussed.
This guide explains how to evaluate the key choices, document the relevant facts, and ask better questions before committing. It focuses on common U.S. consumer situations; local requirements, specific contracts and individual circumstances still matter.
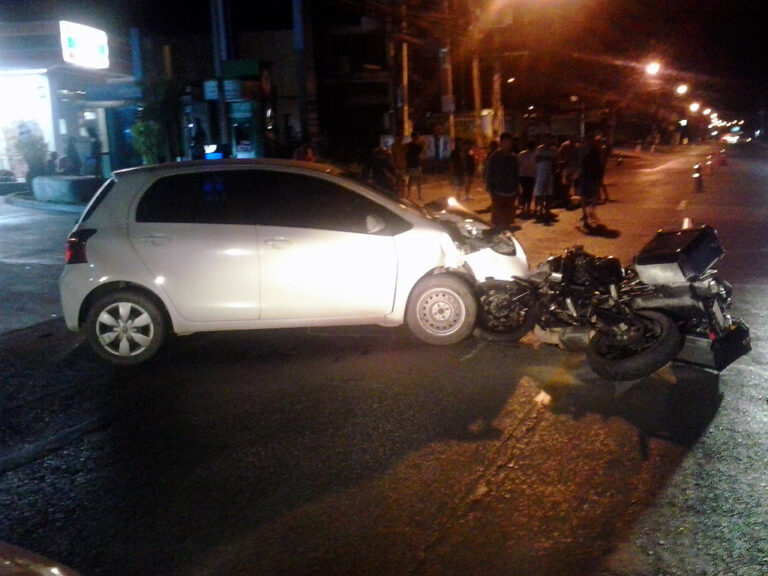
Once safe, capture vehicle positions, visible damage, location, date, witness information and relevant exchange details; follow local reporting requirements and insurer notice rules.
A comparison should use matching deductibles, limits and drivers; otherwise premium differences may reflect different products. The aim is to create a short evidence trail that another qualified person could independently review, rather than basing a decision on memory or a single headline figure.
Separate the evidence-gathering task from choosing a repair shop, and keep copies of estimates, communications and invoices.
A useful comparison separates what each approach solves, what it leaves unresolved, the time or effort involved, and the conditions under which the recommendation would change. Where a provider offers only one path, request an explanation of why plausible alternatives are unsuitable.
Ask for the scope in writing. Identify exclusions, dependencies, approval steps and what happens if new information appears after work begins. The insurer’s declarations page is the controlling quick reference for coverage selections and limits; policy terms provide the detailed rules.
A cheap premium can conceal a high deductible, restrictive coverage or a lower limit. Compare the total annual premium and what you would pay under a plausible loss; do not assume two policies are equivalent just because both are called full coverage.
The most useful comparison is a like-for-like comparison. A lower headline charge may shift work or financial risk onto the customer, while a higher quote may contain meaningful services that the other proposal excludes. Put the assumptions side by side and ask the provider to mark any missing line items.
A driver with a disputed side-impact collision uses dated photographs and a clear event timeline to support a conversation with the adjuster.
The important lesson is not that everyone should reach the same conclusion. It is that the decision follows documented needs, comparable proposals and a clear explanation of what success would look like. A second evaluation is especially valuable when the stakes are high, the diagnosis is uncertain or the alternatives differ substantially.
Never risk physical safety for photographs or make an unsupported admission about who was legally at fault.
Another mistake is overlooking what happens after signing or paying. Keep records of the agreed scope, future obligations, cancellation rules where applicable, and the contact to use if the result does not meet expectations. Ask specifically about a loss scenario rather than relying on general words such as “protected” or “full coverage.”
No. Compare the result being purchased, the quality of the underlying evidence, what is excluded and the practical cost if the option does not work as intended. Seek clarification when two proposals use different assumptions.
Consider another qualified assessment when major expense, safety, legal rights or an irreversible change is involved; when the explanation is unclear; or when estimates propose fundamentally different solutions.
Insurance rules, available coverages, limits, exclusions and claims procedures vary by state, policy and insurer. Verify the declarations page and speak with a licensed insurance professional where appropriate.
Featured image — Photo: Rob Olivera · BY